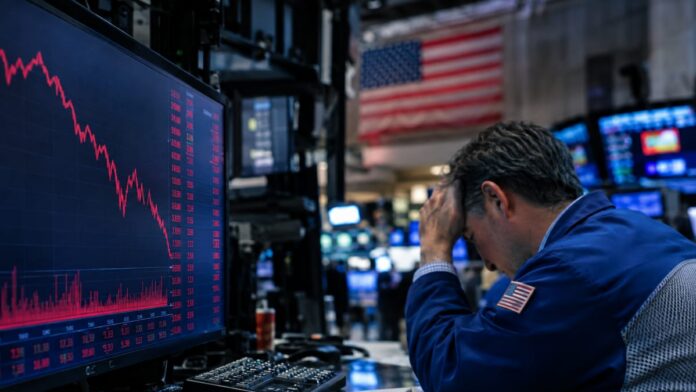
The S&P 500 and the Dow Jones Industrial Average closed in correction territory on Friday, Nov. 20, as a selloff in artificial intelligence stocks spread across Wall Street. The S&P 500 fell 3.7% to 6,910.39, and the Dow dropped 949.73 points, or 1.93%, to 48,147.33.
The Nasdaq Composite lost 5.28% to 22,617.73, wiping out its gain for 2026; it is now down 2.7% for the year. A correction means a drop of at least 10% from a recent high, and both the S&P 500 and the Dow are now more than 11% below their records.
What the numbers show
The S&P 500 set its closing record of 7,818.93 on Oct. 6, and the Dow set its record of 54,349.12 on Aug. 5, according to Federal Reserve Bank of St. Louis data. Friday’s closes leave the S&P 500 11.6% below its peak and the Dow 11.4% below its own. The Nasdaq, which peaked at 27,599.89 on Oct. 6, is 18% off its high.
For the week, the Dow fell 8%, its worst week since March 2020. The S&P 500 lost 8.6%, its worst week since April 2025, and the Nasdaq fell 10%, also its steepest weekly drop since March 2020.
Chip stocks led Friday’s decline. Nvidia slid around 14%, Advanced Micro Devices more than 13% and Micron Technology almost 14%. Anthropic, which jumped 17% in its Nasdaq debut on Thursday, lost 8.5%. Investors moved into defensive names, and Walmart, Costco, Johnson & Johnson and Procter & Gamble all gained.
Why it matters
AI investment has been carrying the economy. It helped U.S. growth reach a 3.4% annual rate in the most recent quarter, NPR reported, and AI-related stocks make up a large share of the S&P 500, which means many 401(k)s and pension funds hold them.
Borrowing costs are part of the pressure. The Federal Reserve raised rates in September for the first time in over three years, which makes it more expensive for AI companies to borrow for data centers.
Politics is another factor. Democrats won both chambers of Congress in the midterms and have promised tougher rules for the AI sector and a slower data-center build-out. Daily Beltway analysis: the selloff turns the new Congress’s tech agenda and the Fed’s next move into direct questions about Americans’ retirement balances. That’s our read.
The administration’s case, and the Fed’s
Asked on CNBC on Friday whether anything had fundamentally changed in the AI story, Treasury Secretary Scott Bessent answered, “No.” He said the market has fallen “since the election as the market looks for some certainty from the Democratic side of the aisle.” He added, “President Trump wants to work with the Democrats. We’ll see if they can work with themselves.”
Bessent also pushed back on talk of a half-point rate hike in December. Lower oil and gasoline prices, he said, will “substantially influence the inflation numbers,” and “I would encourage the Fed to look forward, not backwards.”
Fed Governor Christopher Waller has taken the other view. He said on Wednesday, Nov. 18, that a half-point increase in the Fed’s benchmark rate is probably necessary at the December meeting, warning that inflation is moving the wrong way and spreading. A quarter-point hike paired with a clear signal of another move in January could also work, he said.
What’s next
On Wednesday, Nov. 25, at 8:30 a.m. ET, the Bureau of Economic Analysis will release its second estimate of third-quarter GDP and the October personal income and outlays report, which includes the PCE inflation data the Fed watches. The Fed’s last meeting of the year is Dec. 8 and 9, when it will also release new economic projections.